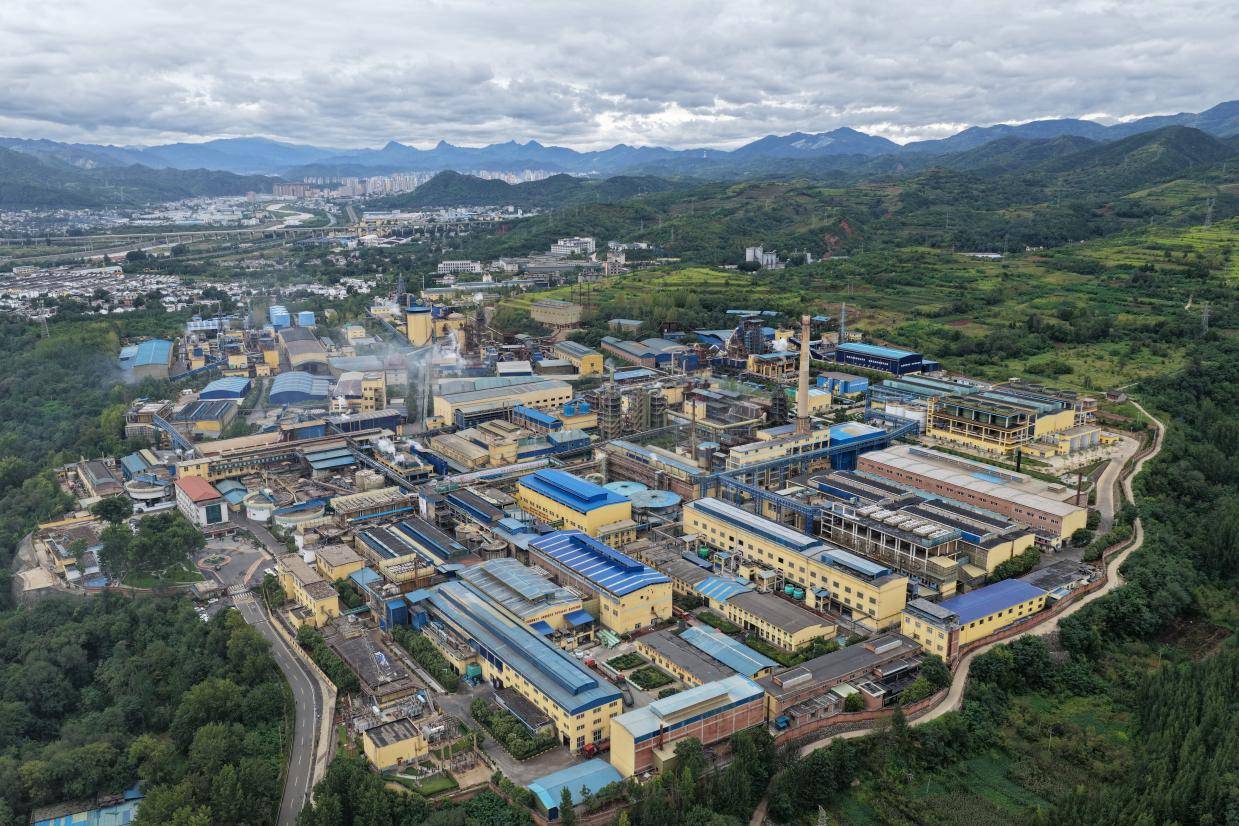
An industrial metal that appears to be ordinary is illustrating how the direction of GSCs has changed. Reuters reported on 6 October that China is shifting this year from a long-term net-finishing country to a potential net exporter. In August alone, China exported 40,668 tons of refined zinc, the second highest level in a single month in 20 years; The cumulative net exports for the first eight months of the year were 4,388 tons.
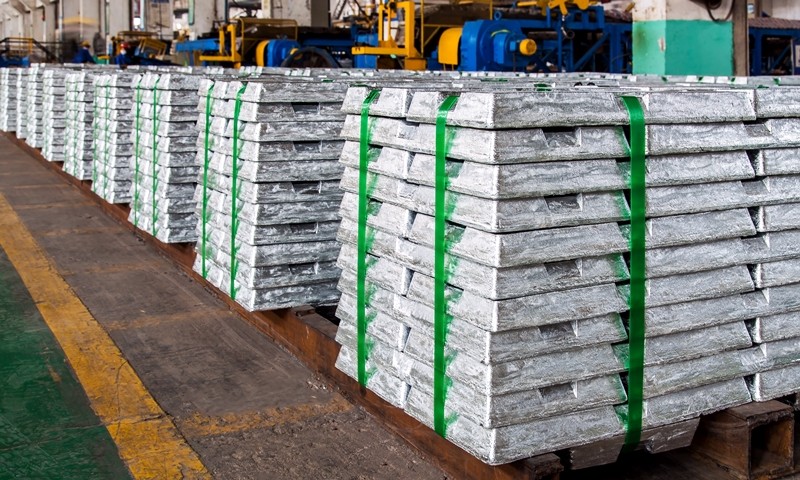
Zinc is used extensively in steel plating, automobiles, construction and infrastructure. In the past, China had large smelting capacity, but its manufacturing and construction sectors had sufficient demand to absorb large volumes of production and therefore still needed imports. The situation is now reversed by weak real estate and domestic demand in China on the one hand, and rising smelting costs, plant production cuts or closure on the other hand, for example, in Europe.
Most notably, the mismatch between price and capacity. The tight stock of the London Metal Exchange has created arbitrage opportunities in Asian markets, and Chinese smelters have transported more zinc to warehouses in Hong Kong, Singapore and Gao Hung. China ' s excess capacity thus not only addresses domestic stockpile pressures, but also begins to fill the Western supply gap.
At the same time, the European smelter industry is experiencing high energy prices and raw materials stress. Projects such as the Budel smelter in the Netherlands are under operational pressure. Once more Western production is out, the global market will rely more on Chinese metal refining.
This is the long-standing strategic effect of China’s industrial policy: to reduce unit costs by using cheap credit, expansion and complete industrial chains over time, before pushing excess production to international markets as domestic demand declines. In the short term, this will stabilize global prices; In the long run, it is likely to accelerate the withdrawal of indigenous smelting capacity in other countries.
After the rare earth, the West has realized that “low-cost Chinese supply” may turn into strategic dependence in times of crisis. Zinc is not as scarce as rare earth, but it suggests that the same mechanism can occur in more common and basic industrial materials. Beijing does not necessarily need to declare export restrictions, but simply to allow factories in other regions to disappear in price competition would be sufficient to change future supply chain bargaining power.
Article discussion
Verified members can discuss this report publicly and manage their own content.
Checking member sign-in status…